Waiting 30-90 days to get paid? Your unpaid invoices could help unlock working capital sooner.
B2B WORKING CAPITAL
Invoice Factoring,
Explained Simply.
Learn how businesses turn unpaid invoices into working capital, what factoring really costs, and how to decide whether it makes sense for your company.
Independent education • Straightforward answers • No-pressure qualification
FUNDAMENTALS & MECHANICS
What Is Invoice Factoring?
Invoice factoring allows a business to sell eligible unpaid customer invoices to a factoring company rather than waiting 30, 60 or 90 days to be paid.
1) You invoice your customer
You complete the work or deliver the product and send your business customer an invoice.
2) A factoring company advances part of the invoice
After approval and verification, the factoring company may advance a large portion of the invoice value.
3) Your customer pays the factoring company
When the customer pays, the remaining balance is released to you minus the agreed factoring fees.
Key Insight: Factoring is generally based heavily on the creditworthiness of the customers paying your invoices, not just your own business credit.
WHY BUSINESSES LOOK AT FACTORING
Your Business Is Growing, But Your Cash Is Tied Up
You can be doing good work and still feel squeezed if customers take 30-90 days to pay. Here are three common reasons business owners start looking into factoring.
Make Payroll
Your customers may pay in 30-90 days, but employees need to be paid every week or two.
Buy Materials or Inventory
New work often requires buying materials, fuel or inventory long before the customer pays.
Take On More Work
A large new contract can create a cash-flow problem before it creates profit.
Factoring does not fix an unprofitable business. It can help otherwise healthy businesses deal with the timing gap between completing work and getting paid.
THE CORE MECHANIC
Invoice Factoring Can Turn Receivables Into Usable Cash
Invoice factoring involves selling eligible unpaid business invoices to a factoring provider. The provider may advance part of the invoice value after approval and verification. Terms vary by agreement.
When your customer pays the provider, any remaining balance is released after agreed fees and adjustments. Advance rates, guarantees, credit checks, liens and accounting treatment depend on the provider and contract.
UNDERWRITING REALITY
What Providers Look For
Providers review your customers, completed work, invoices and business before making a decision.
01. Customers Who Can Pay
Customer credit is important. The provider may also review your business and personal credit.
02. Completed Work and Valid Invoices
Invoices normally need to cover completed work or delivered goods without disputes. Existing liens may affect eligibility.
03. Eligible Invoice Volume
Available advances depend on eligible invoices, customer limits and provider approval.
PRICING & FEE TRANSPARENCY
What Does Factoring
Actually Cost?
Factoring costs depend on your customers, invoice volume, payment timing and agreement. Compare the full cost rather than the quoted percentage alone.
Key variables factoring fees often depend on:
- Customer creditworthiness and solvency strength
- Total monthly and annual invoice volume
- How long customers take to pay (payment terms and collection cycle)
- Industry sector and associated commercial risk profile
- Recourse versus non-recourse factoring agreement terms
- Contract structure and commitment duration
- Minimum monthly or quarterly volume requirements
Important caveat: A quoted percentage rate is meaningless on its own without knowing how often the fee accrues: whether it applies weekly, monthly, as a flat fixed charge, or over a defined invoicing period.
EXAMPLE CALCULATION
“If a company factors a $100,000 invoice at a 3% fee for a specified period, the factoring fee would be $3,000 for that period. Actual fee structures vary significantly.”
Questions to ask before signing
- Is the fee assessed weekly, monthly, or as a fixed charge?
- Are there minimum monthly volume requirements?
- Are there setup, processing, or wire fees?
- Is the agreement recourse or non-recourse?
- Is there a long-term contract requirement?
- Is there an early termination or account closure fee?
The Referral Journey
A Clear Three-Step Process
Here is how we help you understand factoring and take the next step if it looks suitable.
Tell Us About Your Business
Tell us about your customers, invoices and cash-flow needs.
Step 1: Share Your Situation
Understand the Next Step
We help you understand whether factoring may be worth exploring and can introduce you to a factoring provider.
Step 2: Learn and Discuss
Provider Review
The provider verifies your business, customers and invoices and sets any available terms. Approval and funding timing vary.
Step 3: Provider Underwriting
The Factoring Desk provides education and referrals. The factoring provider makes all approval and funding decisions.
STRATEGIC CAPITAL DEPLOYMENT
Outcomes That Drive Growth
Free up cash tied in 30-90 day invoices so your business can grow without waiting on slow payments.
OPERATIONAL CERTAINTY
Keep Payroll and Operations On Time
Eligible invoices may provide cash to help cover payroll and operating expenses while customers take time to pay. Approval and funding timing vary.
Access to cash from eligible invoices after approval
Help covering payroll and operating expenses
A way to bridge customer payment delays
SCALE & EXPANSION
Approach Bigger Contracts With More Confidence
A larger contract can mean buying materials and hiring staff before you get paid. Factoring may help bridge that gap when invoices qualify and fees fit your margins.
- Bid confidently on higher-margin projects
- Complete large stages without heavy bank loans
- Offer better payment terms to customers
ELASTIC FUNDING
Flexible Funding That Grows as Your Billing Does
Available advances may increase as eligible invoice volume grows, subject to customer limits and provider approval. Compare the full cost with other financing options.
Available advances depend on eligible invoices and customer limits
Guarantees and security requirements vary by agreement
Ask whether you can choose invoices or must factor whole accounts
Understand the fees and agreement before deciding.
FINANCING COMPARISON
Factoring vs. Bank Loan
Understand how selling receivables differs from taking on debt and how each option impacts your financial statements.
INVOICE FACTORING
Asset Sale Model
Factoring involves selling eligible receivables. Compare the full fees, obligations and customer payment process before deciding.
Based largely on eligible invoices and customer credit
May cost more than conventional bank financing
Customer payment arrangements may change
Guarantees, liens and accounting treatment vary by agreement
Available advances depend on invoice eligibility and approval
TRADITIONAL BANK LOAN
Debt Liability Model
Loans involve repaying principal plus interest and may include financial covenants and obligations.
Based on the borrower’s financial strength and credit
May offer lower financing costs
May require collateral, guarantees or covenants
Approval time varies by lender and application
Credit limits may be fixed
Key Takeaway: Neither option is automatically better. The right choice depends on your business, cash-flow needs and financing options.
TAILORED CAPITAL BY SECTOR
Industries That Commonly Explore Factoring
These businesses often pay expenses before customers settle invoices. Whether factoring fits depends on the customers, eligible invoices, fees and agreement.
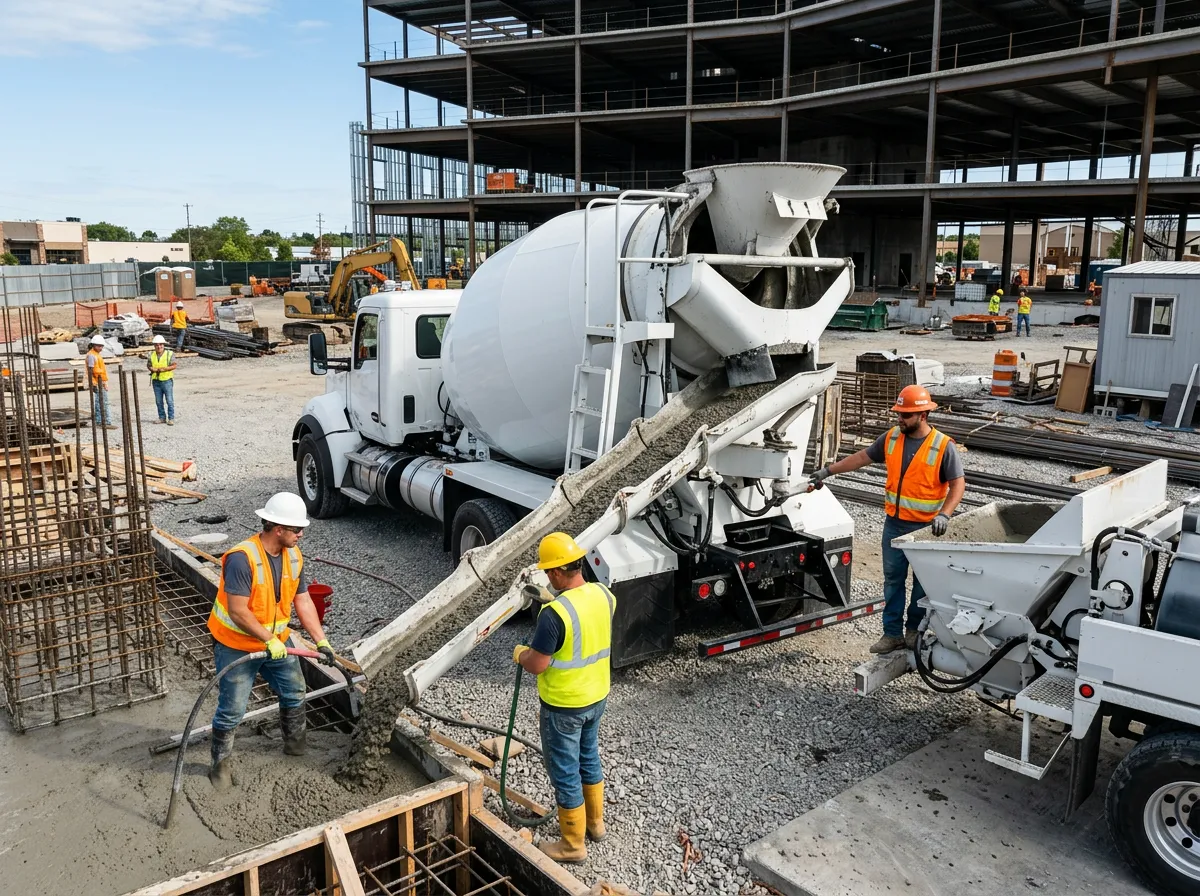
READY-MIX CONCRETE
Ready-Mix Concrete
Ready-mix producers pay for cement, aggregate, fuel, trucks, and drivers up front. Customers may pay after tickets are approved and billing is processed—often net-30 to net-60, sometimes longer. If invoices are accepted and eligible, factoring may help smooth cash flow between pours and payments.
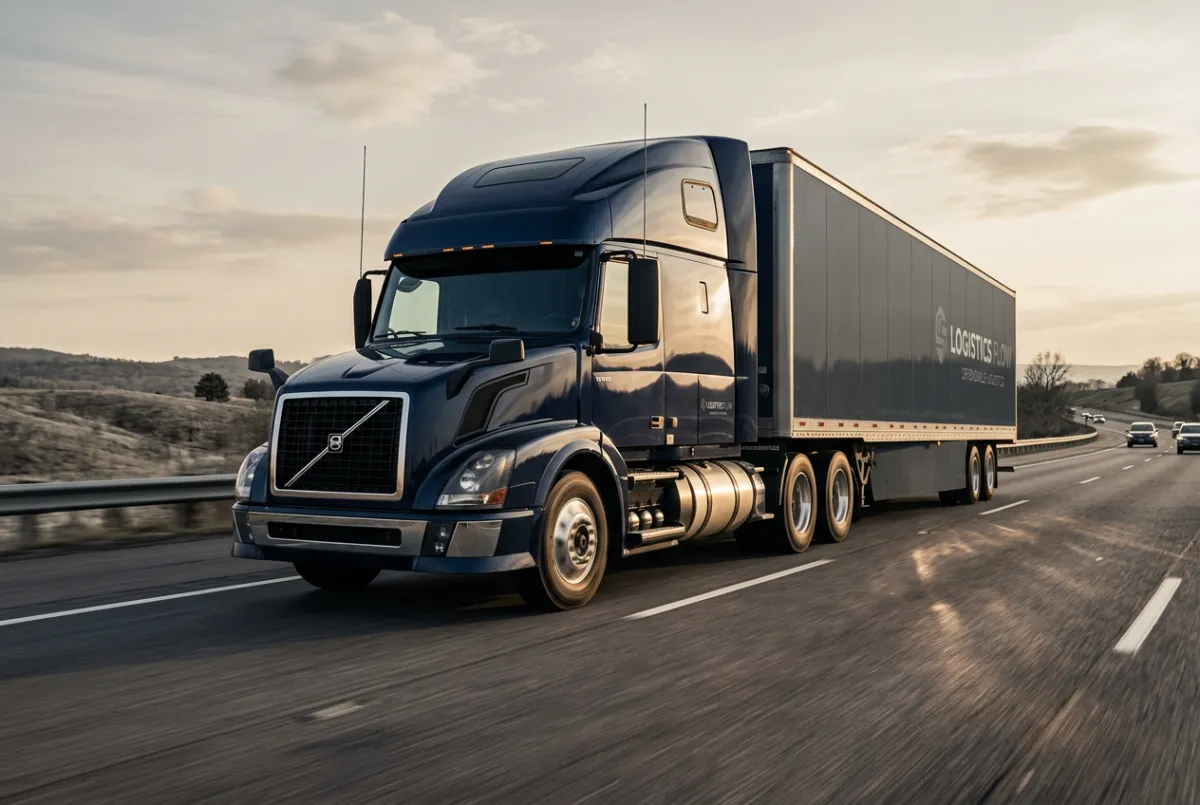
TRUCKING & TRANSPORTATION
Trucking & Transportation
Freight brokers and shippers may pay net-30 to net-60, but fuel, insurance, maintenance, and driver pay can’t wait. If loads are delivered and invoices are clean, factoring may advance part of what you’re owed so cash flow is steadier while you wait. Terms and fees vary.
STAFFING
Staffing
Staffing firms often pay workers weekly and cover payroll taxes, while clients pay 30–60 days after timesheets are approved. That delay can squeeze growth. When invoices are valid and clients are creditworthy, factoring may help cover payroll and recruiting costs while you wait for payment. Approval and pricing vary.
CONSTRUCTION & SUBCONTRACTING
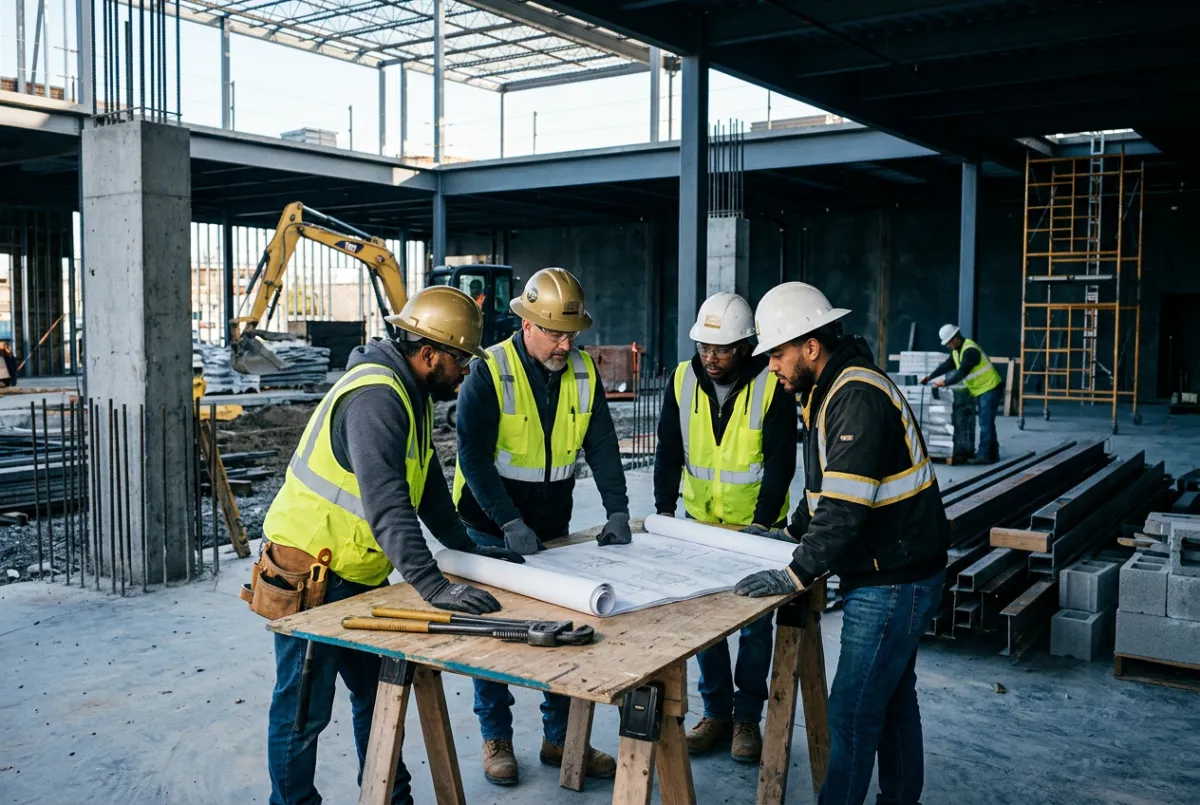
Construction & Subcontracting
Subs buy materials and pay crews before the GC releases progress payments. Pay apps, inspections, change orders, and retainage can push payment out 30–90+ days. If billing is approved and not disputed, factoring may help bridge the timing gap so projects keep moving. Fit depends on contract terms.
OILFIELD & ENERGY SERVICES
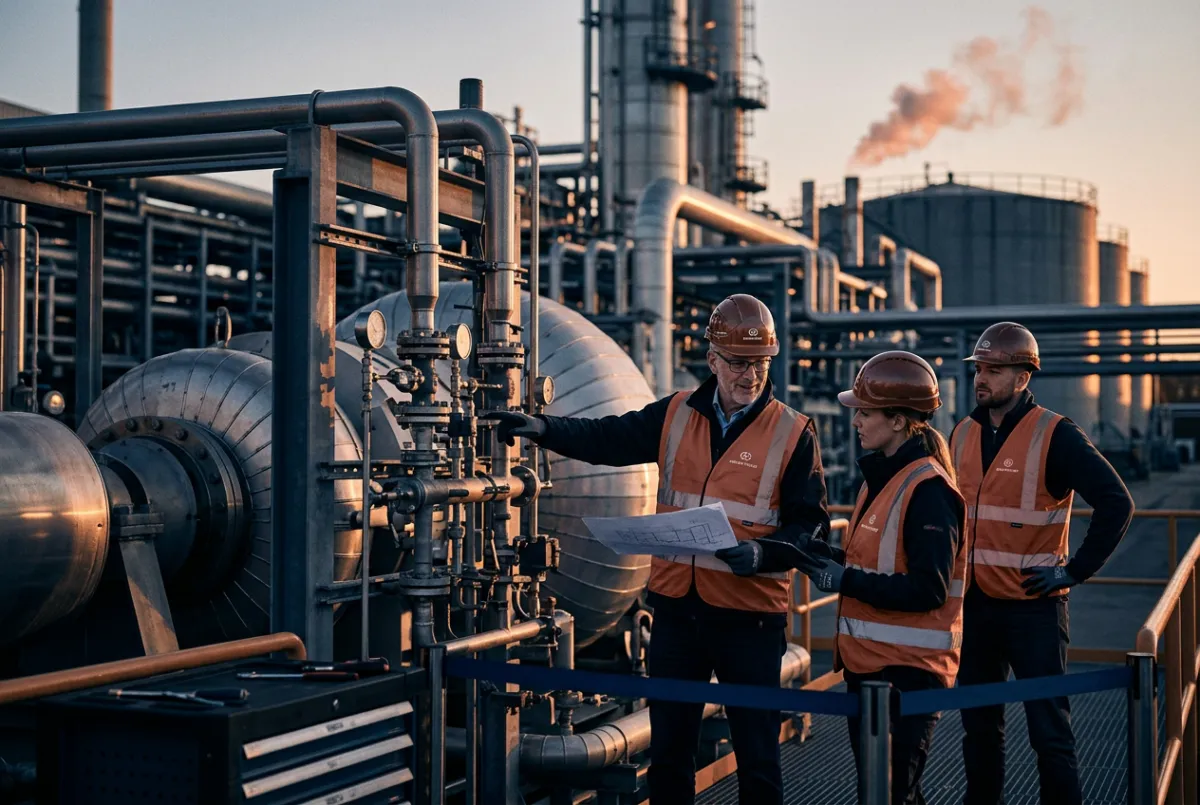
Oilfield & Energy Services
Oilfield and energy service work can involve heavy labor, trucking, and equipment costs before an operator pays. Ticket approval and back-office review can stretch payment to 30–90 days. If invoices are accepted and customers qualify, factoring may help keep cash available for payroll and job costs. Timing and fees vary.
MANUFACTURING
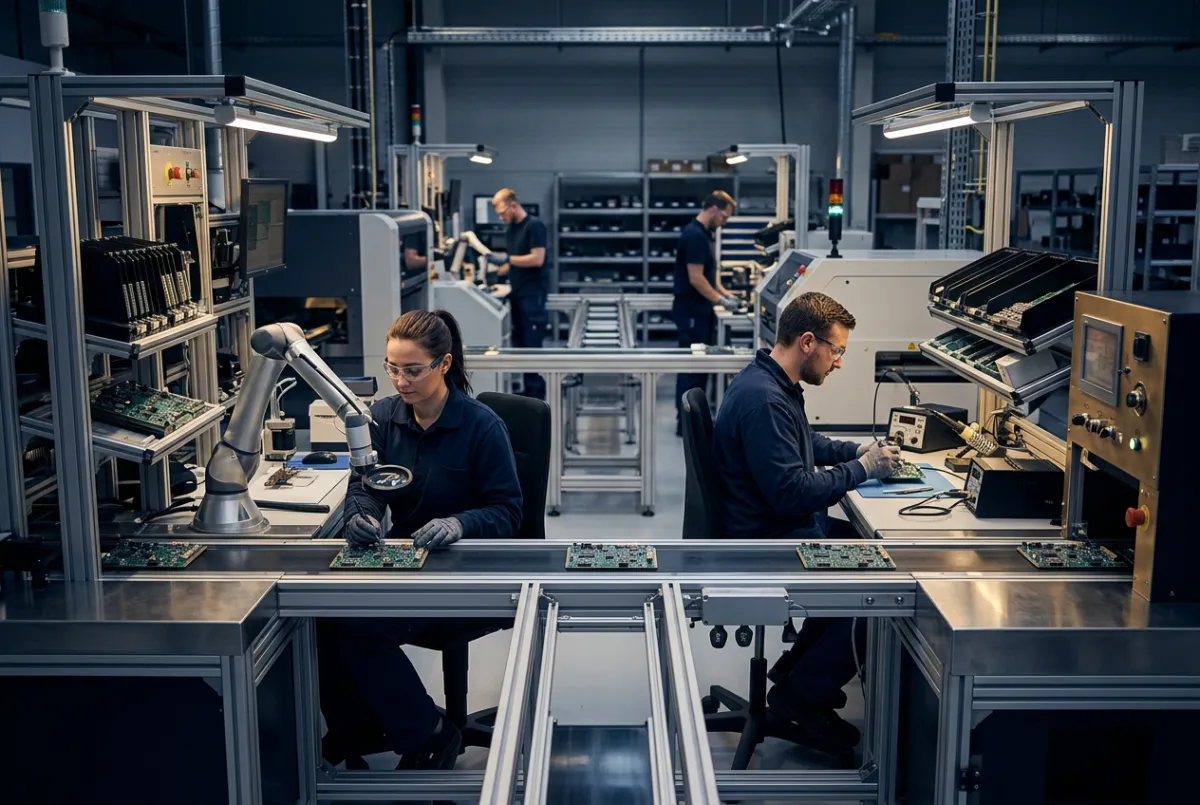
Manufacturing
Manufacturers may pay for materials, labor, and shipping long before a customer pays. Large POs often come with net-30/60 terms and deductions that slow cash flow. For eligible receivables, factoring may provide working capital for production runs and inventory turns. It’s not always a fit—costs vary.
WHOLESALE & DISTRIBUTION
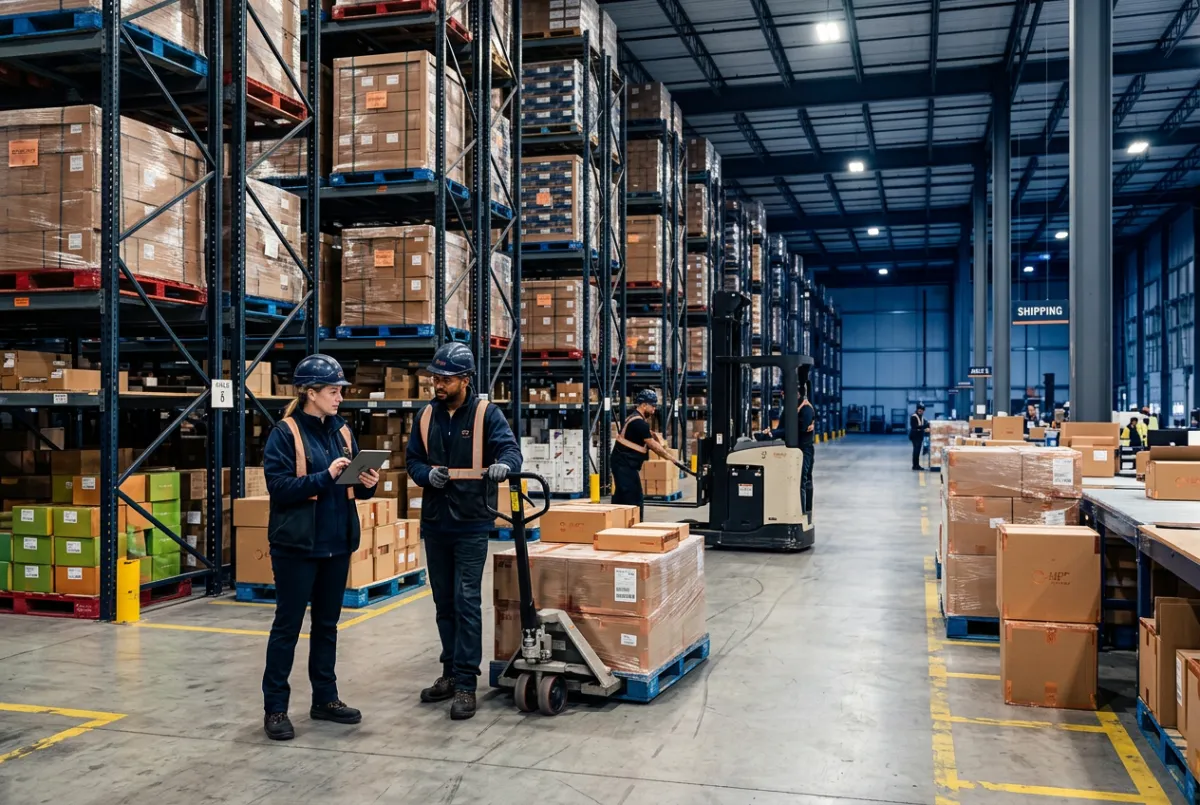
Wholesale & Distribution
Distributors tie up cash in inventory and freight, then extend net-30/45/60 terms to win accounts. A few big orders can strain working capital. If invoices are eligible and customers are creditworthy, factoring may help free cash to restock and ship faster while you wait to be paid. Terms vary.
GOVERNMENT CONTRACTING
Government Contracting
Government agencies may pay reliably, but invoicing rules, approvals, and milestones can slow payment. Net-30 can become net-60+ with paperwork or audits. When invoices are accepted and assignments are allowed, factoring may help shorten the wait for payment. Programs differ, so rules and timelines depend on the provider.
Suitability depends on your customers, invoices and the provider’s review.
BEFORE YOU SIGN
Understand the Agreement
Review the full terms and ask for written answers before deciding whether factoring fits your business.
Ask the provider before you sign
- What is the total cost if a customer pays late?
- When could I have to repay or replace an invoice?
- What guarantees, liens, minimums and termination terms apply?
- How will my customers be notified and where will they pay?
Request a written example using your invoice amount and expected payment timing.
01 · COSTS
Total Cost
Ask how fees accrue, what extra charges apply and how late customer payments change your total cost.
02 · RESPONSIBILITY
Recourse and Guarantees
Understand when you must repay or replace an invoice. Non-recourse terms usually cover specific risks, not every unpaid invoice.
03 · CONTRACT TERMS
Commitments and Exit
Review minimums, renewal dates, notice periods, termination fees, liens and customer payment instructions.
SELF-ASSESSMENT
When Does Factoring Make Sense?
Factoring isn’t for every business. Here are a few simple signs it may (or may not) be worth exploring.
Factoring does not fix an unprofitable business. It can help otherwise healthy businesses deal with the timing gap between completing work and getting paid.
Factoring may be worth exploring if:
- You sell primarily to other businesses or government agencies
- You invoice customers after completing work or delivering products
- Your customers typically pay in 30–90 days
- Your customers are financially established
- Slow payments are limiting growth or creating cash-flow pressure
Factoring may not be the best solution if:
- Most of your customers are individual consumers
- Your invoices are disputed or for unfinished work
- Your margins cannot absorb factoring fees
- You already have access to inexpensive bank financing that meets your needs
TRANSPARENCY & DUE DILIGENCE
Answers to Your Questions
Factoring terms and fees differ widely by provider. Reviewing details early helps avoid surprises.
What does invoice factoring typically cost?
Costs depend on customer credit, eligible invoice volume, payment timing and the agreement. Ask for the full fee schedule and a written example that includes fees for late payments, minimums, wires and termination. A quoted percentage alone does no
Will my customers know I’m factoring invoices?
Most standard agreements notify your customers with a Notice of Assignment, directing payments to the factor. Some providers may offer confidential factoring options for established businesses, letting you manage collections yourself while receiving funding.
Does my personal credit affect my business’s factoring eligibility?
Personal credit usually doesn’t affect eligibility. Factoring approval focuses on your B2B customers’ credit and payment history. Providers may verify business legitimacy but often require less personal credit scrutiny than banks.
What’s the difference between recourse and non-recourse factoring?
With recourse factoring, if your customer doesn’t pay after a set period (e.g., 90 days), you may have to buy back the invoice. Non-recourse protects you if the customer becomes insolvent but usually excludes disputes or delivery issues.
Are there minimums or long-term commitments?
Terms vary. Some require annual contracts and minimum monthly volumes with penalties if unmet. Others offer flexible, invoice-by-invoice funding without quotas. Review renewal and termination fees carefully before agreeing.
How soon are funds released after submitting invoices?
Setup and verification usually take 2–5 business days. Afterward, daily invoices often fund within 24 hours, sometimes same-day via wire, after basic delivery checks.
Is factoring considered balance sheet debt?
Factoring is the sale of an asset (accounts receivable), not a loan. It doesn’t add debt or liabilities to your balance sheet and usually doesn’t affect debt-to-equity ratios or loan covenants.
Can I factor invoices with customer disputes?
Funds are advanced only on undisputed invoices for completed work or goods delivered. Disputes must be resolved or replaced with approved receivables before factoring.
What hidden fees should I watch for?
Watch for setup fees, account maintenance, invoice processing, lockbox administration, credit check charges, wire fees, and minimum fee shortfalls. Transparent providers disclose all fees upfront.
How hard is it to terminate a factoring contract?
Termination policies vary. Contracts often require 30–90 days notice before renewal. Early termination may involve exit or lien release fees. Verify all terms and payoff processes clearly.
What does invoice factoring cost?
Costs depend on customer credit, eligible invoice volume, payment timing and the agreement. Request the complete fee schedule and a written example, including late-payment charges and any minimums.
Will my customers know I’m factoring invoices?
Customers are commonly notified and directed to pay the provider. Ask who handles collections, what notice is sent and whether other arrangements are available.
Does personal credit affect eligibility?
Customer credit matters, but the provider may also review your business and personal credit. Ask what checks, guarantees and security requirements apply.
What is recourse versus non-recourse factoring?
Recourse agreements may require you to repay or replace unpaid invoices. Non-recourse protection covers only the risks specified in the contract; disputes and other nonpayment may remain your responsibility.
Are there minimums or long-term commitments?
Some agreements require minimum volume, minimum fees or a contract term. Review renewal dates, invoice-selection rules, notice periods and termination costs.
How soon are funds released?
Timing depends on onboarding, customer credit review, invoice verification, approval and banking cutoffs. Ask the provider for a timeline for your specific business; same-day funding is not guaranteed.
Is factoring considered balance sheet debt?
Accounting treatment depends on the agreement and applicable accounting rules. Ask your accountant how the transaction, recourse obligations, reserves and existing loan covenants should be treated.
Can I factor disputed invoices?
Providers generally require completed work or delivered goods and valid, undisputed invoices. Ask how disputes, credits, returns and offsets affect eligibility and repayment obligations.
What additional fees should I review?
Ask about setup, administration, credit checks, wires, minimum-volume shortfalls, late payments, renewals, early termination and lien-release charges. Compare the full cost with other financing options.
How do I end a factoring agreement?
Review the notice deadline, automatic renewal, outstanding invoice obligations, termination fees and process for releasing liens and changing payment instructions. Obtain the exit requirements in writing.
Have Questions? We're Here to Help.
Have a question about how factoring works or whether your invoices may fit? Get in touch for a straightforward conversation.
OUR MISSION & PURPOSE
Why The Factoring Desk Exists
Factoring can be incredibly useful for the right business, but the industry can also be confusing. Rates are quoted differently, contracts vary, and many business owners don't know what questions to ask.
The Factoring Desk was created to make the process easier to understand.
We explain how factoring works, the costs to look for and the questions you should ask before signing an agreement.
If factoring appears appropriate for your business, we can also help connect you with a factoring provider and guide you through the process.
Disclosure: The Factoring Desk is an educational and referral platform and is not a lender. We may receive compensation when a business we refer enters into a factoring relationship with one of our factoring partners.
START A CONVERSATION
Could Factoring Work for Your Business?
Answer a few questions about your invoices and we'll help you understand whether factoring may be worth exploring.
Share your contact details below. Include your industry, approximate monthly B2B invoice volume and usual customer payment terms.
No obligation. Submitting an inquiry does not guarantee approval or funding.
Your clear, straightforward guide to B2B invoice factoring options
REFERRAL DISCLOSURE
The Factoring Desk is an educational and referral service, not a lender or factoring provider. We may receive compensation if a referred business enters a factoring relationship. The provider makes all approval and funding decisions. Eligibility, fees, advances and timing depend on its review and agreement. Submitting information does not guarantee approval or funding.
© 2026 Roman Holdings Group LLC, operating as The Factoring Desk.