FACTORING BY INDUSTRY
Manufacturing Invoice Factoring
Manufacturing invoice factoring may provide an advance against eligible customer invoices for goods already delivered and accepted. It is distinct from funding raw materials, work in process or a purchase order for goods that have not been produced.
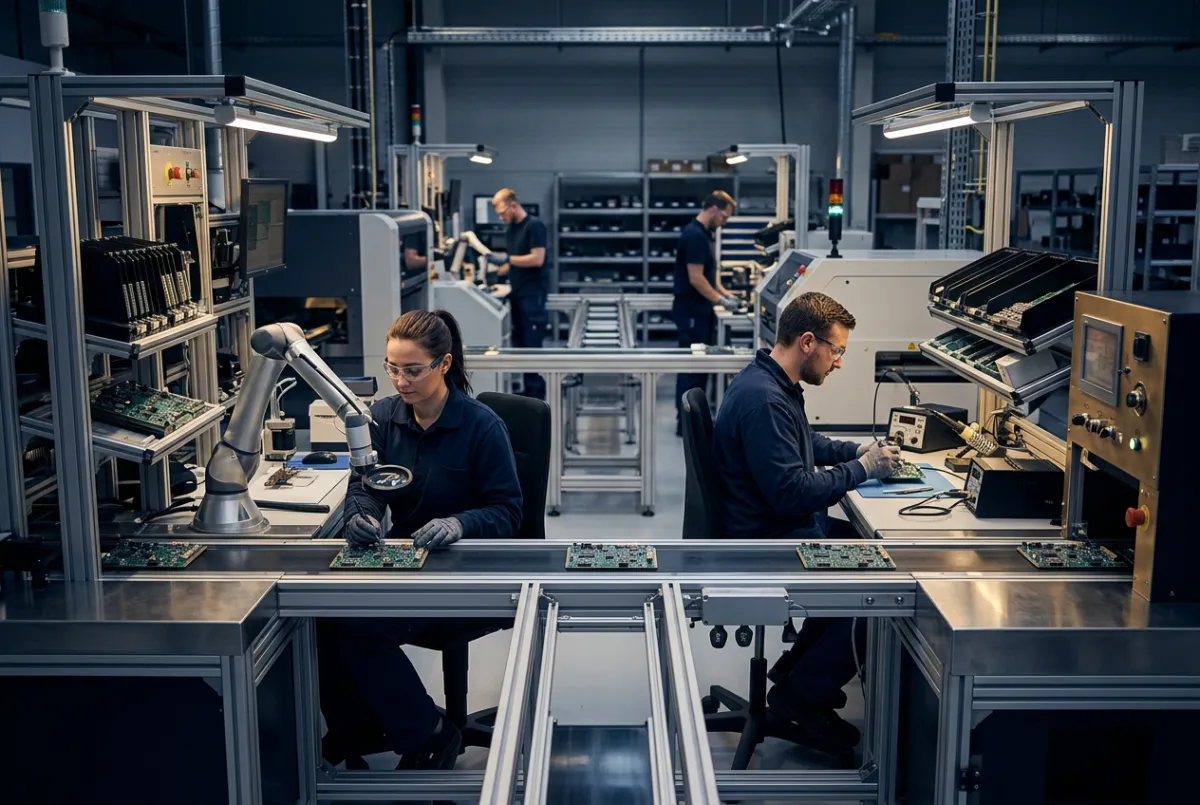
A manufacturer buys materials and pays labor before a finished shipment generates a receivable. Customer payment terms can then delay cash for the next production run. Factoring may shorten the receivables stage of that cycle, but it does not automatically fund the pre-production stage.
Map the production-to-payment cycle
Separate cash spent on raw materials, work in process, finished inventory and customer receivables. Identify where the bottleneck occurs. If cash is needed before the goods exist, discuss purchase-order, inventory or other working-capital financing separately.
If goods are already delivered and billing accepted, list the invoices available for review. Ask whether domestic, export, milestone or related-party receivables are eligible in the provider’s program.
Connect invoices to accepted shipments
Prepare the purchase order, agreed specifications, invoice, packing list and shipping or delivery evidence. Ask whether the customer’s acceptance or inspection is required before an advance.
Custom fabrication, tooling charges, warranties and sale-on-approval arrangements can create additional conditions. Disclose quality complaints, rejected batches, open credits and returns instead of assuming shipment alone proves an unconditional payment obligation.
Account for dilution and concentrated customers
The amount collected can fall below the invoice face value because of returns, rebates, discounts or debit memos. This reduction is often called dilution. Track it by customer and product and ask how it affects eligibility and reserves.
A manufacturer reliant on one OEM may encounter concentration limits. Confirm the approved customer limit before scheduling a larger run on the assumption that all resulting invoices can be funded.
Compare cash released with margin lost
For a hypothetical $50,000 accepted shipment at an 85% advance, initial cash is $42,500. A $1,000 total fee leaves $49,000 of total proceeds if the customer pays in full without adjustments. The retained balance is not all available on day one.
Compare those proceeds with material, labor, freight and overhead commitments. Model delayed payment and returns as separate scenarios, and compare the full fee with a bank line, earlier billing or customer deposits when available.
Documents to prepare for a manufacturing review
- Invoices matched to customer purchase orders
- Shipping records, delivery evidence and required acceptance
- Specifications, inspection records and open quality issues
- Credit memos, rebates, returns and deduction history
- Receivables aging, customer concentration and existing liens
The provider may request additional records. Share business documents through an agreed secure process; an inquiry alone does not establish approval.
Common questions
Can a purchase order be factored before production?
A purchase order is not an invoice for completed delivery. Pre-production funding needs a different review and may call for another financing product.
Will customer returns affect funding?
They can. Returns and credit notes may reduce eligible balances, reserve releases or future availability. Ask how the agreement handles them.
Sources and further reading
altLINE: industry coverage and factoring programs
Provider resources describe their own programs, not universal terms. The planning questions and hypothetical examples on this page are original guidance from The Factoring Desk. Reviewed October 1, 2026.