Ready-Mix Concrete Factoring: From Delivery Tickets to Cash Flow
Ready-mix concrete invoice factoring may provide an advance against eligible receivables for delivered concrete. Fit depends on the customer, accepted billing, supporting delivery records, existing liens and whether fees leave a workable margin.
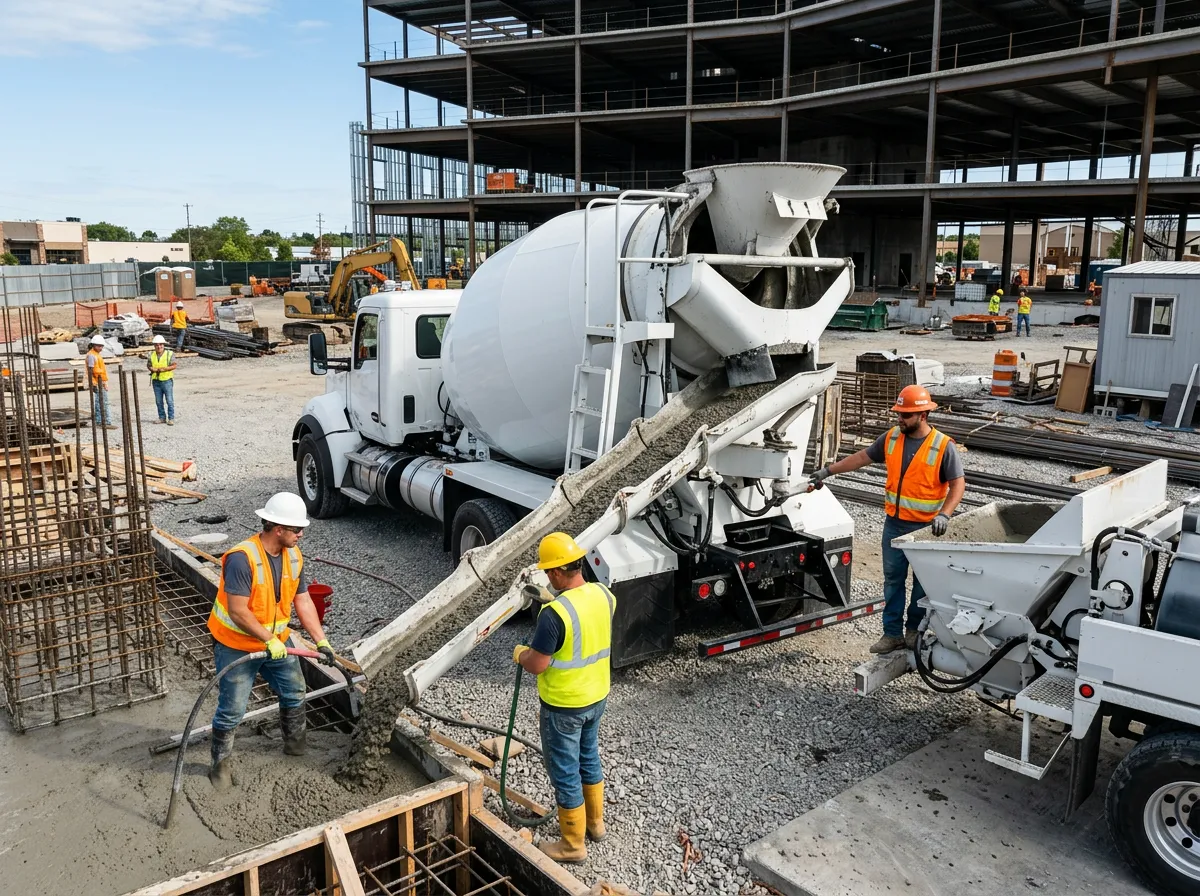
A completed pour does not end the cash cycle. A producer still needs to connect delivery tickets, customer approval, invoicing and payment. When that process stretches out, another busy week can require more fuel, materials and driver payroll before the last week produces cash.
Follow the invoice from the jobsite
Start by identifying the legal customer responsible for payment. A general contractor, subcontractor and property owner are not interchangeable. The billing contact and jobsite contact may also be different people.
Build a clear packet: invoice, purchase order or account agreement where applicable, delivery tickets, job identifiers, quantities and evidence of receipt or acceptance. Ask which documents the provider requires and how it verifies them with the customer.
Keep delivered product separate from future work
An accepted invoice for concrete already delivered is different from a quote for next month’s pours. A factor’s review of an existing receivable should not be mistaken for a commitment to finance future production.
Where the account involves progress billing, retainage, conditional payment clauses or disputed quantities, identify those terms early. Some providers consider progress billing, but eligibility and documentation remain provider-specific. Do not treat the entire receivables ledger as immediately available cash.
Use a margin example before deciding
Imagine a hypothetical $30,000 delivery invoice with $24,000 of direct job costs. The $6,000 difference is 20% of the invoice before overhead and financing. A hypothetical $600 factoring fee reduces that difference to $5,400.
That arithmetic does not establish whether the job is profitable. Dispatch costs, plant expenses, maintenance and other overhead still matter. Calculate the fee against the actual job economics rather than treating faster cash as additional profit.
Make billing accuracy part of the cash plan
Missing tickets and customer deductions can delay verification or reduce what is collected. Reconcile deliveries with invoicing promptly, document agreed surcharges and resolve disagreements before submitting the invoice.
Then forecast the advance separately from the reserve. If you need cash for cement, aggregate, fuel and payroll, compare those due dates with the provider’s confirmed funding process. Leave room for rejected invoices, slower payments and possible recourse obligations. A dependable document process can improve visibility even if you ultimately decide against factoring.
Build a delivery-to-invoice control sheet
A busy plant may have dozens of tickets for one account, with several pours, purchase orders and job locations. Before asking for an advance, reconcile the invoice to the delivered quantities and agreed pricing. A readable packet helps distinguish a routine verification question from a real dispute.
| Check | Match across the records | Resolve before relying on funding |
|---|---|---|
| Customer and job | Legal payer, job number and purchase order | Wrong entity or a missing PO reference |
| Quantity and price | Delivered yards, agreed rate and ticket totals | Returned concrete or quantity disagreement |
| Delivery acceptance | Ticket dates, receipt and required sign-off | Missing or illegible acceptance records |
| Additional charges | Approved waiting time, short-load or other charges | Unapproved extras included in the invoice |
| Open balance | Invoice less payments and credit notes | Credits or deductions not yet posted |
Separate available cash from the gross invoice
For a second hypothetical illustration, suppose the $30,000 invoice above is eligible for an 80% advance. That produces $24,000 initially and leaves $6,000 held back. With a $600 total fee and full collection, the later release would be $5,400. If $26,000 of material, fuel and payroll payments fall due before collection, that advance alone leaves a $2,000 timing gap.
Do not assume the provider will advance against disputed charges or conditional balances. If only part of the invoice is accepted for purchase, recalculate from that eligible amount. Keep the fee assumptions separate from the advance calculation and confirm the actual settlement terms.
Plan for another week of production
Use a weekly schedule for cement and aggregate purchases, fuel, driver payroll and essential plant costs. Mark which invoices have been issued, accepted and approved. Keep tomorrow’s orders separate from today’s receivables: a full dispatch book does not create an invoice for completed delivery.
Before taking a larger job, check customer approval and capacity against the expected outstanding balance. Multiple invoices to one contractor can consume a customer limit while earlier invoices remain unpaid. Ask how that limit is increased and what documents are required.
Finally, review the job’s payment clauses and deductions with the provider. Where a construction contract makes payment conditional, seek advice on the actual contract rather than assuming the delivery ticket settles every payment issue. Better invoice control helps you evaluate factoring and also improves ordinary collections.
Common questions
Can delivery tickets replace an invoice?
A delivery ticket can support proof of delivery, but the provider determines its required invoice and acceptance documentation. Ask for its checklist.
Is construction retainage eligible for factoring?
Do not assume it is. Retainage and conditional or progress billing require specific review of the contract, payment rights and provider program.
Sources and further reading
Provider resources describe their own programs; they do not establish terms for every factoring agreement. This article includes original examples and practical questions from The Factoring Desk.