FACTORING BY INDUSTRY
Ready-Mix Concrete Factoring
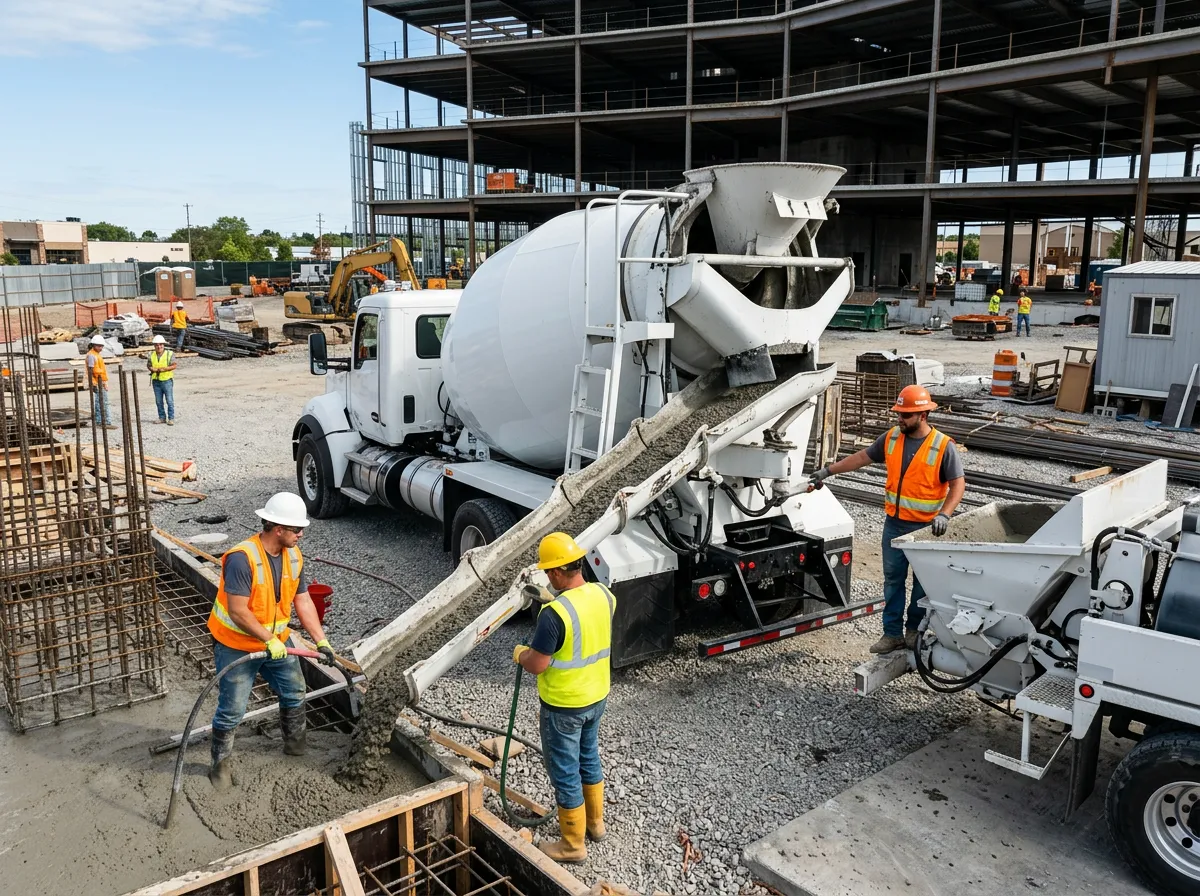
Ready-mix concrete factoring may turn eligible invoices for delivered concrete into working capital before the contractor pays. The provider needs reliable delivery records, an accepted invoice and an approved customer; a scheduled pour or unsigned ticket is not the same as a verified receivable.
A batch plant pays for cement, aggregate, admixtures, drivers and diesel while contractors may still be approving tickets and processing monthly statements. More pours can increase sales and the amount of cash tied up at the same time. Factoring is worth evaluating against this delivery-to-payment gap, using your actual collection history rather than invoice terms alone.
Follow the money from plant to payment
Map the dates when materials are purchased, concrete is dispatched, tickets are signed, invoices are submitted and cash arrives. Separate ready-mix supply invoices from installation or subcontracting pay applications: the supporting evidence and contract conditions can be different.
For a hypothetical $30,000 accepted delivery invoice, an 85% advance would release $25,500 initially. If total fees were $600 and the customer paid in full, the later reserve release would be $3,900. Total proceeds would be $29,400. These figures illustrate the mechanics, not available terms.
Match every invoice to the pour
Prepare delivery tickets showing the customer, job address, delivery date, mix or order reference, quantity and acknowledgment of receipt. Reconcile tickets with the purchase order, agreed price and billed extras such as waiting time or short-load charges.
A receiving signature helps document delivery but does not resolve every quality, quantity or price dispute. Tell the provider about rejected loads, pending credits, backcharges or missing approvals before counting the invoice as available cash.
Check the customer and project conditions
The entity that owes your invoice may be a subcontractor, general contractor or another commercial customer; the project owner is not automatically your account debtor. Ask the factor to approve the correct legal entity and confirm its limit before increasing exposure.
Review any progress-billing conditions, retainage, assignment restrictions and lien or waiver requirements with the provider and your adviser. Ask whether amounts awaiting project certification are eligible. Do not assume a concrete supply invoice is treated like an approved construction draw.
Test the fee against each delivery margin
Compare the full fee at your expected payment date and at a later date. Include wire charges, minimums, reserve rules and any obligation to repurchase unpaid or disputed invoices.
Check whether faster access to cash preserves enough contribution after materials, hauling and plant costs. Negotiate clearer ticket approvals and invoice submission routines alongside funding; preventable billing delays can create additional financing costs.
Documents to prepare for a ready-mix concrete review
- Recent accounts receivable aging and customer payment history
- Invoices reconciled to signed delivery tickets and purchase orders
- Agreed prices, accepted extras and outstanding credit notes
- Customer legal names, billing contacts and project requirements
- Existing receivables financing, liens and relevant supply contracts
The provider may request additional records. Share business documents through an agreed secure process; an inquiry alone does not establish approval.
Common questions
Can future pours be factored?
Standard invoice factoring is generally for existing receivables supported by delivered goods or completed work. A purchase order or planned delivery needs separate review and may require a different financing product.
Can disputed loads or retainage be included?
Do not assume so. The provider must review disputes, acceptance conditions and any retainage; it may exclude those amounts or hold additional reserves.
Sources and further reading
Crown Financial: invoice mechanics and progress billing
Provider resources describe their own programs, not universal terms. The planning questions and hypothetical examples on this page are original guidance from The Factoring Desk. Reviewed October 1, 2026.